Surgeons

Quick Guide: Medical Malpractice Insurance for California Plastic Surgeons

2026-10-06T10:24:50+00:00

GET A QUOTE

Medical Malpractice Insurance

Summary

California plastic surgeons buying malpractice insurance need to understand claims-made vs. occurrence coverage, how the state’s MICRA damage caps shape claim exposure, what drives premium cost, and when tail coverage is required. California is considered one of the more stable malpractice markets in the country thanks to MICRA, but that doesn’t mean coverage decisions are simple, especially for a specialty with California’s volume of elective, out-of-pocket procedures.

Dos and Don’ts

Do

  • Confirm your coverage limits meet every facility’s privileging requirements.
  • Ask about consent-to-settle rights before signing with any carrier.
  • Disclose every med spa or medical director role you hold.
  • Compare tail coverage costs before switching carriers.
  • Check a carrier’s financial strength rating, not just its premium.
  • Document informed consent conversations in detail, every time.
  • Understand how MICRA’s damage caps do, and don’t, limit your exposure.
  • Work with a broker to find the best medical malpractice rates for plastic surgeons.

Don’t

  • Don’t lock in the lowest limits without confirming what your facility will actually accept.
  • Don’t sign a policy without knowing whether it carries a hammer clause.
  • Don’t count on coverage from a former employer following you to your next role.
  • Don’t let a claims-made policy expire without lining up tail or nose coverage first.
  • Don’t pick a carrier on price and skip everything else.
  • Don’t start shopping the week your policy renews.
  • Don’t treat MICRA’s noneconomic cap as a ceiling on everything you could owe.

California-Specific Legal Factors to Know

Medical Malpractice Insurance Not Required by Law, but Required by Most Facilities

  • California law does not require physicians to carry medical malpractice insurance.
  • That’s not the same as optional if you plan to practice.
  • Under California Health & Safety Code § 1319, hospitals and health facilities are permitted to make professional liability coverage a condition of medical staff membership, and most do.
  • Most cosmetic plastic surgery in California happens in an accredited outpatient surgical facility or office-based setting rather than a hospital, so credentialing requirements will typically come from the facility, not a hospital medical staff office.

California Caps Non-economic Damages in Medical Malpractice Cases under MICRA

  • For 2026, that cap is $470,000 for cases that don’t involve a patient death, and $650,000 for wrongful death cases.
  • Both figures are scheduled to keep rising each year through 2033.
  • Economic damages, including future medical costs and lost earning capacity, are uncapped, which is where a serious plastic surgery complication can still produce a large claim.

Statute of Limitations

  • The statute of limitations for a California medical malpractice claim is 3 years from the date of injury or 1 year from discovery, whichever comes first.
  • This is the window to keep in mind when deciding how long a tail policy needs to run.
Plastic Surgeon Reducing Risk Of Malpractice Claim By Talking With Patient

Types of Malpractice Coverage: Claims-Made vs. Occurrence


Claims-Made Occurrence
Coverage Trigger Policy must be active when the incident occurs AND when the claim is filed Policy just needs to be active when the incident occurred
Typical Premium Pattern Lower in early years, rises as the policy “matures” (step-rated) Higher flat premium from year one
Tail Coverage Needed? Yes, it’s necessary when coverage lapses, switching carriers, retiring, or closing the practice No
Most Common for Employed / group-practice physicians, cost-conscious early-career surgeons Surgeons who want cost certainty and no future tail-coverage decision

What Drives the Cost of Plastic Surgery Malpractice Insurance in California?

Factor Effect on Premium
Procedure Types Body-contouring and fat-grafting cases carry higher rates than injectables or minor skin work. Peer-reviewed claims data shows body, breast, and facial procedures make up a disproportionate share of plastic surgery malpractice litigation.
Claims History A prior claim raises your rate going forward, even one that was closed without a payout.
Coverage Limits Carrying higher limits raises the premium, and your facility’s credentialing rules may set the floor for how high.
Practice Structure Solo practitioners, group-rated physicians, and employer-covered physicians are all priced differently.
Location in California Metro areas with high procedure volume and litigation activity, think Los Angeles, Orange County, and the Bay Area, carry higher rates than the state’s less populated regions.

Frequently Asked Questions

No, California law does not require private-practice physicians to carry malpractice insurance. In practice, the surgical facility you operate in almost always sets its own minimum coverage requirement as a condition of granting you privileges, under authority the state gives facilities through Health & Safety Code § 1319.

It comes down to timing. A claims-made policy must be active at both the time of the incident and when the claim is filed. An occurrence policy covers anything that happened while it was active, regardless of when the claim eventually gets filed.

Exposure is only partially limited under MICRA. MICRA caps noneconomic damages, currently $470,000 for a non-death case and $650,000 for a wrongful death case in 2026, but economic damages like future medical care and lost income are uncapped. A complication requiring extensive corrective treatment can still generate a claim well beyond the noneconomic cap.

It depends on procedure mix, claims history, coverage limits, practice structure, and where in the state you practice. California is often cited as one of the more moderate malpractice markets because of MICRA, but plastic surgery is a higher-risk specialty within any state. Also, rates in dense, litigation-active metro areas tend to run higher than in less populated parts of California.

Don’t assume it does. Acting as a medical director or overseeing NPs, PAs, or aestheticians introduces a different kind of exposure, and it’s worth confirming with your carrier that delegated care is covered at every site where you are a supervisor.

Protect Your Business and Find Competitive Rates with SURGPLI

California’s MICRA framework, credentialing expectations, and claims-made-vs-occurrence decisions all affect what the right coverage looks like for your practice, and getting it right takes some research.

SURGPLI is an educational resource built specifically for plastic surgeons researching medical malpractice insurance. Our goal is to help you understand coverage types, what drives your premium, and the right questions to bring to whichever carrier or broker you choose to work with.

Learn More from SURGPLI

Browse our other California and plastic surgery resources to keep learning, or explore our full library to compare how coverage works in other states.

Read the latest From SURGPLI

Contact us for a MEDICAL MALPRACTICE INSURANCE quote

Quick Guide: Medical Malpractice Insurance for California Plastic Surgeons2026-10-06T10:24:50+00:00

Quick Guide: Illinois Plastic Surgeon Malpractice Insurance

2026-09-30T15:52:48+00:00

In This Guide

GET A QUOTE

Medical Malpractice Insurance

Summary

Illinois plastic surgeons buying malpractice insurance need to understand claims-made vs. occurrence coverage, what drives premium cost, when tail coverage is required, and how to compare carriers. Premiums for Illinois plastic surgeons typically range from $80,000–$150,000+ annually at standard $1M/$3M limits — Illinois is rated as a high-risk state for the specialty, with Chicago/Cook County practices often quoted near $90,000 or more, depending on procedure mix, claims history, and coverage limits.

Dos and Don’ts

Do

  • Confirm your coverage limits meet every facility’s privileging requirements — Illinois sets no statewide minimum, so facilities set the floor themselves.
  • Ask about consent-to-settle rights before signing with any carrier.
  • Disclose every med spa or medical director role you hold.
  • Compare tail coverage costs before you switch carriers.
  • Check a carrier’s financial strength rating, not just its premium.
  • Document informed consent conversations in detail, every time.
  • Start shopping for coverage 60–90 days before renewal.

Don’t

  • Don’t assume Illinois requires malpractice insurance by law — it doesn’t, but your hospital or surgery center still will.
  • Don’t sign without knowing if it’s a hammer clause.
  • Don’t assume employer-provided coverage follows you outside that job.
  • Don’t let a claims-made policy lapse without a tail or nose-coverage plan.
  • Don’t shop on premium alone.
  • Don’t wait until renewal week to start comparing carriers.
  • Don’t assume Illinois caps non-economic damages — the state Supreme Court has struck down every attempt to do so.

Illinois-Specific Legal Factors to Know

  • Illinois does not require physicians to carry malpractice insurance by law
    • It’s one of the few states with no statutory malpractice insurance mandate at all — but that doesn’t make coverage optional in practice
  • Hospitals, surgery centers, and credentialing boards almost always require proof of coverage
    • They will be at set minimum limits before granting privileges
  • Illinois courts have twice struck down legislative caps on non-economic damages
    • Most recently in Lebron v. Gottlieb Memorial Hospital (2010), which found the 2005 cap unconstitutional — carriers price Illinois risk with that uncapped exposure in mind
Plastic Surgeon Reducing Risk Of Malpractice Claim By Talking With Patient

Types of Malpractice Coverage: Claims-Made vs. Occurrence

Claims-made insurance covers a claim only if the policy is active both when the incident occurred and when the claim is filed. Occurrence insurance covers any incident that happened during the policy period, even if the claim is filed years later, regardless of whether the policy is still active.


Claims-Made Occurrence
Coverage trigger Policy must be active when the incident occurs AND when the claim is filed Policy just needs to be active when the incident occurred
Typical premium pattern Lower in early years, rises as the policy “matures” (step-rated) Higher flat premium from year one
Tail coverage needed? Yes — if switching carriers, retiring, or closing the practice No
Most common for Employed / group-practice physicians, cost-conscious early-career surgeons Surgeons who want cost certainty and no future tail-coverage decision

What Drives the Cost of Plastic Surgery Malpractice Insurance in Illinois?

Malpractice insurance premiums for Illinois plastic surgeons are shaped primarily by procedure mix, claims history, coverage limits, practice structure, and location within the state.


Factor Effect on Premium
Procedure mix Higher for body-contouring / fat-grafting; lower for injectables or minor skin procedures
Claims history Higher after any prior claim — even one that didn’t result in payout
Coverage limits Higher limits cost more, and may be mandated by facility credentialing requirements
Practice structure Varies by employment model — solo, group-rated, or employer-provided
Location in Illinois Cook County (Chicago) and the collar counties typically rated higher than downstate Illinois

Frequently Asked Questions

Illinois does not require physicians to carry malpractice insurance by law — it’s one of the few states without a statutory mandate. In practice, though, hospitals, surgery centers, and credentialing boards almost always require proof of coverage at specified limits before granting privileges.

Claims-made insurance covers a claim only if the policy is active both when the incident occurred and when the claim is filed. Occurrence insurance covers any incident that happened during the policy period, even if the claim is filed years later.

Cost depends primarily on procedure mix, claims history, coverage limits, practice structure, and location within Illinois. Cook County practices are typically rated higher due to the county’s litigation climate and history of high jury verdicts.

Not automatically. If you serve as a medical director or supervise NPs, PAs, or aestheticians performing procedures, confirm your policy explicitly covers claims arising from delegated care at every location.

Get an Illinois Plastic Surgery Malpractice Insurance Quote

The uncapped damages environment and cosmetic-surgery-specific risk in Illinois, make coverage type, limits, and tail coverage genuinely consequential decisions. Determining the best option for you and your practice is crucial.

Ready to see how SURGPLI can help protect your practice?

SURGPLI is a resource for surgeons to use to compare malpractice insurance options. Explore your options today.

Read the latest From SURGPLI

Contact us for a MEDICAL MALPRACTICE INSURANCE quote

Quick Guide: Illinois Plastic Surgeon Malpractice Insurance2026-09-30T15:52:48+00:00

Illinois Orthopedic Surgeons’ Guide to Medical Malpractice Insurance

2026-10-05T15:57:31+00:00

Jump to a Section

GET A QUOTE

Medical Malpractice Insurance

Illinois Orthopedic Surgeons Guide to Medical Malpractice Insurance

Illinois orthopedic surgeons in private practice can use this guide, prepared by SURGPLI, for a concise overview of medical malpractice insurance. Then contact SURGPLI to discuss your coverage needs and get a quote.

Illinois Orthopedic Surgeons Need Robust Malpractice Coverage

Illinois is recognized as a destination for innovative orthopedic surgery. Rush University Medical Center in Chicago was ranked #9 in the nation for high-performing orthopedic surgical care on the 2026-2027 “Best Hospitals Honor Roll” by U.S. News and World Report. Illinois orthopedic surgeons specializing in foot and ankle procedures, sports medicine, and orthopedic trauma surgery are in constant demand as patient volumes increase statewide.

At the same time, Illinois is also among the top 10 most litigious U.S. states for medical malpractice. In 2025, Illinois saw 413 medical malpractice payouts totaling $266,430,750. That’s why Illinois orthopedic surgeons need robust and affordable medical malpractice coverage.

SURGPLI will help you find the right coverage at the best rate in Illinois.

Medical Malpractice Insurance Dos and Don’ts for Illinois Orthopedic Surgeons

Do

  • Carry at least $1,000,000/$3,000,000 in coverage, the standard limit most Illinois hospitals and surgical facilities expect, even though state law doesn’t mandate it.
  • Choose a carrier rated “A” or better for financial strength, not just the lowest quoted premium, given how much exposure a single Illinois claim can carry.

Don’t

  • Don’t assume “not legally required” means “not needed.” Facility credentialing and practical liability exposure make coverage essential.
  • Don’t shop for coverage alone. Comparing carriers and rates without a broker who works specifically with orthopedic surgeons makes it easy to miss better options at a competitive price.

Cost of Medical Malpractice Insurance for Illinois Orthopedic Surgeons

Carriers consider factors such as practice location, surgical specialty, and past claims history. In Illinois, the areas that typically carry the highest rates are: Chicago (Cook County); Madison and St. Clair Counties (Metro East Illinois counties adjacent to the Greater St. Louis, MO, area).

Approximate medical malpractice insurance premium rates for orthopedic surgeons across Illinois:

Specialty Approximate Claims-Made Rate Approximate Tail Rate Approximate Occurrence Rate
Orthopedic surgery $100,000 $200,000 $125,000

*Using the IL standard limits of $1,000,000 each claim / $3,000,000 aggregate per year in coverage. These rates are estimates only and can vary widely depending on the location and the claims history of each physician.

Types of Professional Liability Insurance for Illinois Orthopedic Surgeons

Claims-Made Insurance

  • Provides coverage if the policy is active when the incident took place AND when the claim is filed.
  • If a claim is filed after the end of the policy date, the claim is NOT covered.
  • Tail malpractice insurance is required to cover claims filed after your policy ends.

Occurrence Insurance

  • Provides coverage for incidents that occurred during the policy year, regardless of when a claim is reported to the carrier.
  • More costly at the start of the policy, but the rate does not “step up.”
  • No need for tail coverage when the policy ends.

Tail Insurance

Reach out to SURGPLI to do the legwork for you to find a tail policy at a great price.

Let SURGPLI Help You Choose the Best Policy for Your Practice

Every medical specialist’s situation is unique, so we recommend a conversation with SURGPLI. We will explain the benefits so you get the right type and amount of coverage at the best rate.

Get Quotes from A-rated Carriers Serving Illinois Orthopedic Surgery

SURGPLI insurance brokers will obtain quotes for medical malpractice insurance from carriers rated “A” by A.M. Best for their long-term financial solvency and robust legal support of policyholders. Some of the top carriers include:

  • The Doctors Company (TDC)
  • ISMIE
  • MedPro Group
  • Coverys Group

Why Orthopedic Surgeons Are Classified as High Risk by Medical Malpractice Insurance Companies

Medical malpractice insurance underwriters classify orthopedic surgery as a high-risk specialty because surgical errors or post-surgical complications can devastate a patient’s mobility, physical well-being, and quality of life. These include high-risk surgeries for total knee and hip replacement, spinal fusion and laminectomy, and procedures on the hand and foot.

Top Reasons Why Illinois Orthopedic Surgeons Are Sued

A review of malpractice claims by The Doctors Company, an “A” rated medical malpractice insurance carrier, found that the top three major orthopedic surgical injuries were related to “an aggravated or worsened preoperative condition,” including increased pain, decreased mobility, nerve damage, and post-operative pain. Other potential orthopedic errors that most often trigger malpractice litigation include:

  • Surgical site infections causing post-operative complications
  • Extensive bleeding in spinal procedures
  • Major blood vessel injury
  • Post-operative deep vein thrombosis and pulmonary embolism

In addition, some of the most often cited allegations in Illinois orthopedic surgery medical malpractice cases include:

  • Failure to diagnose fractures
  • Improper treatment of fractures
  • Failure to diagnose nerve impingement
  • Operating on the wrong body part
  • Improper placement of a replacement bone

Orthopedic surgeons can reduce their risk of a malpractice lawsuit by implementing a comprehensive risk management strategy.

Illinois’ Medical Malpractice Insurance Legislation

Consult SURGPLI to understand the complexities of Illinois’ medical malpractice laws.

Illinois’ Damage Caps on Medical Malpractice Lawsuits

  • No limit on compensation for economic and non-economic patient injuries.
  • No awards for punitive damages in medical malpractice lawsuits.

Illinois’ Statute of Limitations for Medical Malpractice Claims

According to state law, conditions for filing a medical malpractice lawsuit in Illinois are:

  • Within two (2) years from the date the patient knew or should have known of the injury
  • Illinois law prohibits patients from bringing a lawsuit more than four (4) years after the medically negligent act occurred
  • There is a special statute of limitations for patients who are minors at the time the medical malpractice occurred. Anyone under the age of 18 has up to eight (8) years to file a lawsuit, as long as the suit is filed before the patient turns 22.

Orthopedic Surgery Medical Malpractice Outcomes in Illinois

With no cap on economic damages and non-economic damages, orthopedic surgeons in Illinois are more vulnerable to personal financial loss without medical malpractice insurance. The following examples of Illinois medical malpractice lawsuits found in favor of the plaintiff or settled show the critical need for orthopedic surgeons to have strong liability coverage:

$1.1 Million Settlement
An orthopedic surgeon was sued for alleged surgical negligence after the 57-year-old patient was left with unequal leg lengths after hip replacement surgery.

Jury Awards $820,000
The plaintiff brought suit alleging negligent nerve injury to the right hand during surgery for carpal tunnel release.

How SURGPLI Brokers Help Orthopedic surgeons Save Time and Money on Medical Malpractice Insurance

Working with SURGPLI takes the guesswork and effort out of trying to get the right coverage at the best rate on your own. We help you save time and money by:

  • Finding your best “A”-rated carrier options for your specialty and location in Illinois
  • Flagging discounts you may qualify for such as new practice, association membership, claims-free history, or risk management and CME credits
  • Comparing flexible payment options that fit your practice’s budget
  • Walking you through quotes and discounts to help you choose the right coverage

Have Questions? Need a Quote? Ask SURGPLI

SURGPLI is ready to help you navigate the complexities of Illinois medical malpractice insurance. From submitting your application, obtaining the best rates for new policies and renewals from “A” rated carriers, and more, SURGPLI is the only medical malpractice insurance resource you’ll need.

Get a fast quote for medical malpractice insurance or call us at 1-800-969-1339.

Max Schloemann

About the Author

Max Schloemann is a medical malpractice insurance broker, focused on helping physicians secure Medical Professional Liability coverage. He helps Doctors and Surgeons, as well as Physician Assistants, Nurse Practitioners, and healthcare entrepreneurs launch new medical practices across the country. Max graduated Magna cum Laude from Southern Illinois University College of Business and was named the Outstanding Management Senior. Max’s career in medical malpractice insurance began in 2008 with an industry-leading firm. Max founded SURGPLI in 2023 to help surgeons navigate the complexities of medical malpractice insurance in the new era of healthcare. Max’s wife, Kristen, a Physician Assistant, and their 4 kids (plus 1 dog) enjoy hiking, golf, and cooking.

Read the latest From SURGPLI

Contact us for a CA MEDICAL MALPRACTICE INSURANCE quote

Illinois Orthopedic Surgeons’ Guide to Medical Malpractice Insurance2026-10-05T15:57:31+00:00

California Orthopedic Surgeons Guide to Medical Malpractice Insurance

2026-10-05T15:55:35+00:00

Jump to a Section

GET A QUOTE

Medical Malpractice Insurance

California Orthopedic Surgeons Guide to Medical Malpractice Insurance

For California orthopedic surgeons in private practice, this guide is a concise overview of medical malpractice insurance. Contact SURGPLI to discuss your coverage needs and get a quote.

California Is a Destination for Orthopedic Surgery

California has the largest number of orthopedic surgeons in the U.S., according to 2024 data from the U.S. Bureau of Labor Statistics. It is also a highly litigious state with approximately 16.9 medical malpractice lawsuits brought for every 100,000 residents (Source: National Practitioner Data Bank).

SURGPLI will help you find the right medical malpractice coverage at the best rate in California.

Medical Malpractice Insurance Requirements for California Orthopedic Surgeons

Dos

  • Obtain adequate coverage so you can have admitting privileges at California facilities.
  • Work with SURGPLI to find A-rated carriers at the best rates.

Don’ts

  • Don’t do the absolute minimum by skipping medical malpractice insurance just because it’s not required by law.
  • Don’t carry limits below California’s standard $1M/$3M.

Cost of Medical Malpractice Insurance for California Orthopedic Surgeons

Carriers consider factors such as practice location, surgical specialty, and past claims history.

The following are approximate medical malpractice insurance premium rates for orthopedic surgeons across all California areas:

Specialty Approximate Claims Made Rate Approximate Tail Rate Approximate Occurrence Rate
Orthopedic surgery $40,000 $80,000 $50,000

*Using the CA standard limits of $1,000,000 each claim / $3,000,000 aggregate per year in coverage

Get Quotes from A-rated Carriers Serving California Orthopedic Surgeons

SURGPLI insurance brokers will obtain quotes for medical malpractice insurance from carriers rated “A” by A.M. Best for their long-term financial solvency and robust legal support of policyholders. Some of the top carriers include:

  • The Doctors Company
  • Medical Protective
  • Coverys Group
  • Lone Star Alliance RRG
  • CAP MPT
  • MIEC

Types of Professional Liability Insurance for California Orthopedic Surgeons

Claims-Made Insurance

  • Provides coverage if the policy is in effect both when the incident took place AND when the claim is filed.
  • If a claim is filed after the end of the policy date, the claim is NOT covered.
  • Tail malpractice insurance is required to cover any claims made after your policy ends.

Occurrence Insurance

  • Provides coverage for incidents that occurred during the policy year, regardless of when a claim is reported to the carrier.
  • Occurrence policies are more costly at the start of the policy but then stay constant.
  • No need for tail coverage when the policy ends.

Tail Insurance

  • Covers the time after the policy ends and the statute of limitations for when a claim can be made.
  • When switching employers or policies, you should seek tail coverage options.
  • A new employer’s policy is not going to cover you for prior acts of a former practice; tail coverage will.

Read more about tail malpractice insurance for orthopedic surgeons.

Reach out to an experienced SURGPLI insurance broker who will do the legwork for you to find a tail policy at a great price.

Top Reasons Why California Orthopedic Surgeons Are Sued

The top three major orthopedic surgical injuries were related to “an aggravated or worsened preoperative condition,” including increased pain, decreased mobility, nerve damage, and post-operative pain. Other potential orthopedic errors that most often trigger malpractice litigation include:

  • Surgical site infections causing post-operative complications
  • Extensive bleeding in spinal procedures
  • Major blood vessel injury
  • Deep vein thrombosis and pulmonary embolism post-operative

In addition, some of the most often cited allegations in California orthopedic surgery medical malpractice cases include:

  • Misdiagnosis of ACL tear
  • Delayed diagnosis of Achilles tendon rupture
  • Failure to recognize and/or treat post-surgical infections
  • Surgical injuries leading to permanent disability
  • Implant failure leading to infection

Consulting SURGPLI to understand the complexities of California’s medical malpractice laws will ensure your orthopedic surgery practice has the right amount of coverage.

California’s Damage Caps on Medical Malpractice Lawsuits

AB35, signed into law in 2022 and effective January 1, 2023, made the first changes to California’s MICRA non-economic damage caps since 1975. The caps rise annually and now stand at:

  • $470,000 for non-death cases (up from $350,000 in 2023), climbing to $750,000 by 2033
  • $650,000 for wrongful death cases (up from $500,000 in 2023), climbing to $1 million by 2033
  • After 2033, both caps adjust 2% annually for inflation

AB35 also allows patients to collect economic damages from up to three separate sources in one case: doctors, hospitals, and unaffiliated providers such as private-practice specialists.

There is no limit on economic damages, such as actual costs of the medical care necessitated by the malpractice, lost income, lost future earning capacity, and any other measurable economic losses attributable to the defendant’s malpractice.

California’s Statute of Limitations for Medical Malpractice Claims

The following are the major guidelines for California’s statute of limitations for medical malpractice claims:

  • Must be filed within three years after the date of injury or one year after the injury is discovered
  • No filing deadline for cases where a foreign object was left in the patient
  • Exceptions made when the health care provider intentionally acts to defraud the patient or hide a mistake
  • Claims for minors under the age of six must be filed “within three years of the occurrence of the malpractice, or prior to the child’s eighth birthday, whichever timeline provides a larger filing window”

Orthopedic Surgery Medical Malpractice Outcomes in California

The total medical malpractice payout in California was $341,331,800 in 2025. The following examples of California medical malpractice lawsuits found in favor of the plaintiff, or paid as a settlement, show the critical need for orthopedic surgeons to have strong liability coverage:

Jury Awards $1.2 Million
The jury found that the surgeon was negligent in performing ACL surgery, which resulted in the patient needing vascular surgery for an aneurysm that cut off blood circulation to the leg and foot. The patient required three additional vascular surgeries.

Jury Awards $532,521
The plaintiff suffered the amputation of the left leg above the knee as a result of the surgeon’s misdiagnosis of a post-surgical infection, which led to necrotizing fasciitis.

How SURGPLI Helps Orthopedic Surgeons Save Time and Money on Medical Malpractice Insurance

  • Researching your best coverage, rate, and “A” rated carrier options for your specialty and practice location in California.
  • One application for multiple quotes.
  • Policy discounts possible for new practices, medical association members, or physicians with no previous claims.
  • Flexible payment options for your practice.
  • Reviewing and consulting with you to help you make the best choice of coverage and rate for your needs.

Have Questions? Need a Quote? Ask SURGPLI.

SURGPLI is ready to help you navigate the complexities of California’s MICRA medical malpractice tort reforms and secure the right amount of coverage for your orthopedic surgery practice.

Get a fast quote for medical malpractice insurance or call us at 1-800-969-1339.

Max Schloemann

About the Author

Max Schloemann is a medical malpractice insurance broker, focused on helping physicians secure Medical Professional Liability coverage. He helps Doctors and Surgeons, as well as Physician Assistants, Nurse Practitioners, and healthcare entrepreneurs launch new medical practices across the country. Max graduated Magna cum Laude from Southern Illinois University College of Business and was named the Outstanding Management Senior. Max’s career in medical malpractice insurance began in 2008 with an industry-leading firm. Max founded SURGPLI in 2023 to help surgeons navigate the complexities of medical malpractice insurance in the new era of healthcare. Max’s wife, Kristen, a Physician Assistant, and their 4 kids (plus 1 dog) enjoy hiking, golf, and cooking.

Read the latest From SURGPLI

Contact us for a CA MEDICAL MALPRACTICE INSURANCE quote

California Orthopedic Surgeons Guide to Medical Malpractice Insurance2026-10-05T15:55:35+00:00

Quick Guide: Medical Malpractice Insurance for Maryland Plastic Surgeons

2026-09-26T16:18:21+00:00

In This Guide

GET A QUOTE

Medical Malpractice Insurance

Summary

Maryland plastic surgeons buying malpractice insurance need to understand claims-made vs. occurrence coverage, what drives premium cost, when tail coverage is required, and how to compare carriers. Premiums for Maryland plastic surgeons typically run around $50,000 annually in the Baltimore area, with practices near the D.C. suburbs often priced higher, depending on procedure mix, claims history, and coverage limits.

Dos and Don’ts

Do

  • Confirm your coverage limits are in compliance with each facility’s privileging requirements.
  • Ask about consent-to-settle rights before signing with any carrier.
  • Disclose every med spa or medical director role you hold.
  • Compare tail coverage costs before deciding on a new carrier.
  • Check a carrier’s business reputation and standing, not just the premium.
  • Document informed consent conversations in detail, every time.
  • Work with your broker to make sure you are getting the best premium from a trusted company.

Don’t

  • Don’t choose the cheapest option without checking facility requirements.
  • Don’t sign without knowing if it’s a hammer clause.
  • Don’t assume employer-provided coverage lasts after you leave the job.
  • Don’t let a claims-made policy lapse without a tail or nose-coverage plan.
  • Don’t wait until renewal week to start comparing carriers.
  • Don’t assume Maryland’s damage caps limit your exposure.

Maryland-Specific Legal Factors to Know 

No Statutory Requirement, But Check Facility Requirements

  • Maryland doesn’t require physicians to carry malpractice insurance by law.
  • If you go without it, you must notify patients in writing at their first visit and post that fact at your practice.
  • Hospitals, surgery centers, and health plans almost always require proof of coverage anyway, typically $1M/$3M, before granting privileges or network access.

Damage Caps

  • Noneconomic damages are capped at $920,000 for a single claimant in 2026, rising to $1,150,000 in wrongful death cases with two or more beneficiaries.
  • Since economic damages have no cap, you face unlimited risk if the claim includes items such as lost wages or additional medical care costs.  

Statute of Limitations

  • Someone can file a claim within 5 years of the alleged malpractice, or 3 years from discovery, whichever comes first.
  • This window determines how long a tail policy needs to run.
Plastic Surgeon Reducing Risk Of Malpractice Claim By Talking With Patient

Types of Malpractice Coverage: Claims-Made vs. Occurrence

Claims-Made Occurrence
Coverage Trigger Policy must be active when the incident occurs AND when the claim is filed Policy just needs to be active when the incident occurred
Typical Premium Pattern Lower in early years, rises as the policy “matures” (step-rated) Higher flat premium from year one
Tail Coverage Needed? Yes, it’s necessary when coverage lapses, switching carriers, retiring, or closing the practice No
Most Common for Employed / group-practice physicians, cost-conscious early-career surgeons Surgeons who want cost certainty and no future tail-coverage decision

What Drives the Cost of Plastic Surgery Malpractice Insurance in Maryland?

Factor Effect on Premium
Procedure Type Higher for body-contouring / fat-grafting; lower for injectables or minor skin procedures
Claims History Higher after any prior claim, even if it didn’t result in a payout
Coverage Limits Higher limits cost more, and may be determined by facility credentialing requirements
Practice Structure Varies by employment model: solo, group-rated, or employer-provided
Location in Maryland Practices near the D.C. suburbs and Baltimore metro typically see higher premiums than more rural parts of the state

Frequently Asked Questions

No, medical malpractice insurance is not required by statute. Maryland leaves the decision to the physician. If you go without it, you must notify patients in writing at their first visit and post a notice at your practice stating you’re uninsured. In addition, hospitals, surgery centers, and health plans routinely make proof of coverage at specified limits a condition of privileges or network participation, so “not required” rarely translates to “not necessary.”

The difference is in whether or not you need gap coverage. A claims-made policy responds only if it’s active at the time of the incident and when the claim is filed. If you switch carriers or retire, you can expose yourself unless you add tail coverage. An occurrence policy locks in coverage for anything that happened while it was active, no matter how much later the claim shows up.

Medical malpractice insurance costs vary by the nature of the procedure, claims history, coverage limits, practice structure, and where in the state you practice. As a benchmark, Baltimore-area plastic surgeons typically see premiums around $50,000 a year, while practices closer to the D.C. suburbs tend to pay more for coverage.

No, your risk is not capped according to Maryland’s damage cap. The cap only applies to noneconomic damages, currently $920,000 for a single claimant in 2026, and doesn’t touch economic damages like lost wages or future medical care. If a complication leads to long-term treatment or lost earning capacity, a claim can still climb well past seven figures.

Not automatically. If you’re acting as a medical director or overseeing NPs, PAs, or aestheticians who perform procedures, don’t assume that coverage extends to their work by default. Your carrier should confirm that delegated care explicitly covers every location where it happens.

Get a Maryland Plastic Surgery Malpractice Insurance Quote

Between the damage caps, the credentialing expectations, and the tail-coverage decisions built into a claims-made policy, this isn’t a purchase to make on autopilot. Finding the right combination of coverage type, limits, and terms takes real thought, and the right broker can help.

Ready to see how SURGPLI can help protect your practice?

SURGPLI works specifically with Maryland plastic surgeons, so we already understand the risk profile, carrier options, and how to get the best pricing for private practice surgeons. Get your quote today.


Read the latest From SURGPLI

Contact us for a MEDICAL MALPRACTICE INSURANCE quote

Quick Guide: Medical Malpractice Insurance for Maryland Plastic Surgeons2026-09-26T16:18:21+00:00

Quick Guide: Medical Malpractice Insurance for New York Plastic Surgeons

2026-09-26T16:18:41+00:00

In This Guide

GET A QUOTE

Medical Malpractice Insurance

Summary

New York plastic surgeons buying malpractice insurance need to understand the difference between claims-made vs. occurrence coverage, what drives premium cost, when tail coverage is required, and how to compare carriers. Premiums for New York plastic surgeons range from 65,000–110,000 annually. The New York City metro area is usually rated among the highest-cost territories in the country.

Dos and Don’ts

Do

  • Confirm your primary coverage meets New York’s Excess Medical Malpractice Insurance Program threshold and every facility’s privileging requirements.
  • Ask about consent-to-settle rights before signing with any carrier.
  • Disclose every med spa, medical-director, or MSO-affiliated role you hold.
  • Compare tail coverage costs before you switch carriers.
  • Check a carrier’s financial strength rating, not just its premium.
  • Document informed consent conversations in detail, every time.
  • Start shopping for coverage 60–90 days before renewal.

Don’t

  • Don’t choose the cheapest limits without checking what your facility, or the Excess Program, actually requires.
  • Don’t sign without knowing there’s a hammer clause.
  • Don’t assume employer-provided coverage follows you outside that job.
  • Don’t let a claims-made policy lapse without a tail or nose-coverage plan.
  • Don’t shop on premium alone.
  • Don’t wait until renewal week to start comparing carriers.
  • Don’t assume New York caps non-economic damages the way many other states do, it doesn’t.

New York-Specific Legal Factors to Know

  • New York doesn’t have one blanket statute requiring every private-practice physician to carry malpractice insurance.
    • But participating in the state’s Excess Medical Malpractice Insurance Program requires primary coverage at a defined minimum limit, commonly cited as $1M/$3M
  • Hospitals, surgery centers, and credentialing boards almost always require proof of coverage.
    • They will be at set minimum limits before granting privileges
  • Most plastic surgery happens in-office, not in a hospital.
    • Office-based procedures under sedation, anesthesia, or larger-volume liposuction trigger accreditation and adverse-event reporting under Public Health Law §230-d

Types of Malpractice Coverage: Claims-Made vs. Occurrence

Claims-made insurance covers a claim only if the policy is active both when the incident occurred and when the claim is filed. Occurrence insurance covers any incident that happened during the policy period, even if the claim is filed years later, regardless of whether the policy is still active.

Claims-Made Occurrence
Coverage trigger Policy must be active when the incident occurs AND when the claim is filed Policy just needs to be active when the incident occurred
Typical premium pattern Lower in early years, rises as the policy “matures” (step-rated) Higher flat premium from year one
Tail coverage needed? Yes, if switching carriers, retiring, or closing the practice No
Most common for Employed / group-practice physicians, cost-conscious early-career surgeons Surgeons who want cost certainty and no future tail-coverage decision

What Drives the Cost of Plastic Surgery Malpractice Insurance in New York?

Malpractice insurance premiums for New York plastic surgeons are shaped by:.

Factor Effect on Premium
Procedure mix Higher for body-contouring / fat-grafting; lower for injectables or minor skin procedures.
Claims history Higher after any prior claim, even one that didn’t result in payout
Coverage limits Higher limits cost more, and may be mandated by facility credentialing or Excess Program requirements
Practice structure Varies by employment model, solo, group-rated, employer-provided, or MSO-affiliated
Location in Florida NYC (five boroughs), Long Island, and Westchester typically rated higher than upstate New York

Frequently Asked Questions

New York doesn’t have a single statute requiring every private-practice physician to carry malpractice insurance, but in practice it’s close to mandatory. Physicians who want to participate in the state’s Excess Medical Malpractice Insurance Program must carry primary coverage at a defined minimum limit, and hospitals, surgery centers, and credentialing boards almost always require proof of coverage at specified limits before granting privileges.

Claims-made insurance covers a claim only if the policy is active both when the incident occurred and when the claim is filed. Occurrence insurance covers any incident that happened during the policy period, even if the claim is filed years later.

Cost depends primarily on procedure mix, claims history, coverage limits, practice structure, and location within New York. New York City, Long Island, and Westchester practices are typically rated higher due to the downstate litigation climate and uncapped non-economic damages.

Not automatically. New York’s corporate practice of medicine doctrine changes who can own a med spa, but it doesn’t remove the liability question for the supervising physician. If you serve as a medical director or supervise NPs, PAs, or aestheticians performing procedures, confirm your policy explicitly covers claims arising from delegated care at every location.

Get a New York Plastic Surgery Malpractice Insurance Quote

New York’s litigation climate and cosmetic-surgery-specific risk make coverage type, limits, and tail coverage genuinely consequential decisions. Determining the best option for you and your practice is crucial.

Ready to see how SURGPLI can help protect your practice?

SURGPLI works specifically with New York plastic surgeons, which means we already understand the risk profile, the carrier fine print, the Excess Program’s requirements, and the coverage gaps most generic malpractice policies miss.

Read the latest From SURGPLI

Contact us for a MEDICAL MALPRACTICE INSURANCE quote

Quick Guide: Medical Malpractice Insurance for New York Plastic Surgeons2026-09-26T16:18:41+00:00

Surgery as a Career in 2026: Salary, Demand & Risk Outlook

2026-06-11T05:48:40+00:00

Surgery remains one of the most demanding and rewarding career paths in medicine. In 2026, the field is evolving fast as the population ages, technology advances, and reimbursement and regulatory pressures reshape practice.

Demand for surgical care is rising, and many specialties remain among the highest-paid in healthcare. But the path comes with real tradeoffs, including intense training, workload strain, and increased malpractice risk.

This article breaks down the surgical career outlook in 2026, including demand, compensation, emerging technologies, and the key opportunities and risks surgeons should understand.

Table of Contents

What Do Surgeons Do?

Surgeons are physicians trained to diagnose conditions that require operative treatment and to perform procedures that restore function, relieve pain, and save lives. While the public often associates surgery with the operating room, a surgeon’s responsibilities extend well beyond the procedure itself.

Surgeons are involved in every phase of patient care, including:

  • Preoperative diagnosis & evaluation
  • Surgical intervention & operative decision-making

  • Postoperative management & ongoing patient care

  • Leadership and coordination of the surgical team, including anesthesiologists, nurses, surgical assistants, and other specialists

Where Do Surgeons Work?

According to the American College of Surgeons, standard workplace settings for a surgeon include:

  • Hospitals
  • Academic Medicine
  • Private Practice
  • Ambulatory Surgery Centers
  • Contract Assignments Through Staffing Agencies
  • Institutional Practice
  • Government Service Programs
  • Military/Uniformed Services

Professional Advantages for Surgeons in 2026

The following factors contribute to a favorable outlook for surgeons in 2026 and beyond:

  1. Growing Market Value in the U.S.
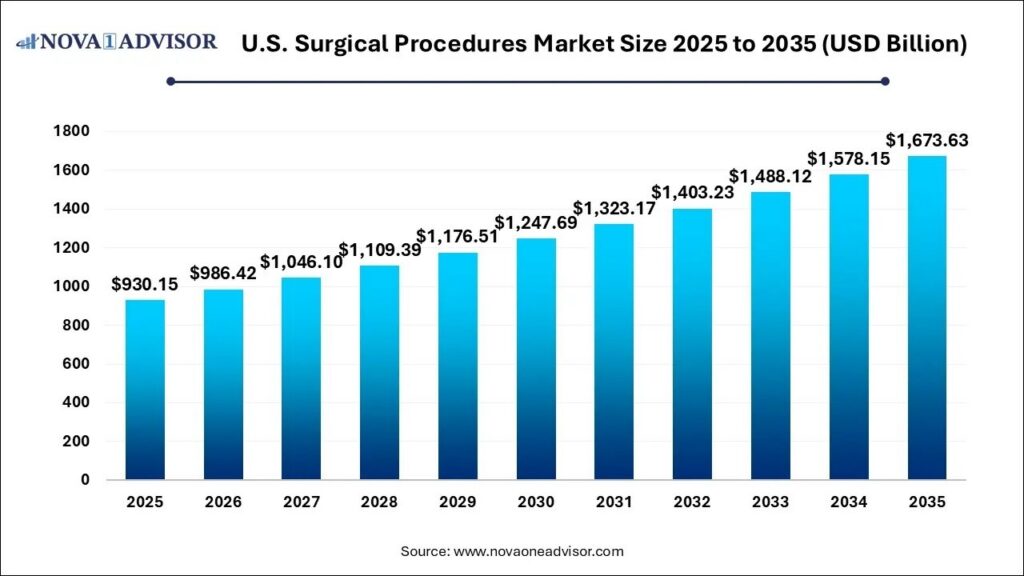
    The U.S. Surgical Procedures Market measured $930 billion in 2025 and is expected to reach around $1.67 trillion by 2035.

These market growth predictions indicate that surgeons will experience considerable flexibility and autonomy with employment opportunities.

U.S. Surgical Procedures Market Size (2025-2035)

U.S. Surgical Procedures Market Size

Surgical procedures in the United States are expected to reach a market value of $986 billion in 2026 and $1.67 trillion by 2035.
Source: Nova One Advisor

  1. Increasing Demand for Surgery
    According to the U.S. Bureau of Labor Statistics, physician and surgeon employment is projected to grow 3% between 2024 and 2034, with 23,600 openings projected each year during that time.
Projected Employment Growth for Surgeons by Specialty, 2024-2034
Specialty Employment, 2024 Projected Employment, 2034 Projected Growth, 2024-2034
All physicians & surgeons 839,000 863,200 3%
Ophthalmologists, except pediatric 12,500 13,100 4%
Orthopedic surgeons, except pediatric 14,700 15,300 4%
Pediatric surgeons 1,100 1,100 2%
Surgeons, all other 25,100 26,100 4%

The projected growth rate varies across specialties, with most surgical specialties expected to grow at rates above the 3% physician/surgeon average.
Source: U.S. Bureau of Labor Statistics

Why is the Demand for Surgeons Increasing?

      • Several factors are driving increased demand for surgical specialists in the United States. One of the most significant is the aging Baby Boomer population, which increases surgical demand while also contributing to workforce shortages.

Key contributing factors to surgeon demand:

        • Aging General Population
          According to the World Health Organization, the world’s population aged 60 or older will double by 2050. An older population typically requires more surgical interventions, including orthopedic hip and knee replacements, interventional cardiology, and cataract surgeries. This explains why ophthalmologists’ and pediatricians’ employment projections have the highest and lowest expected growth rates, respectively.
        • Aging Surgical Workforce
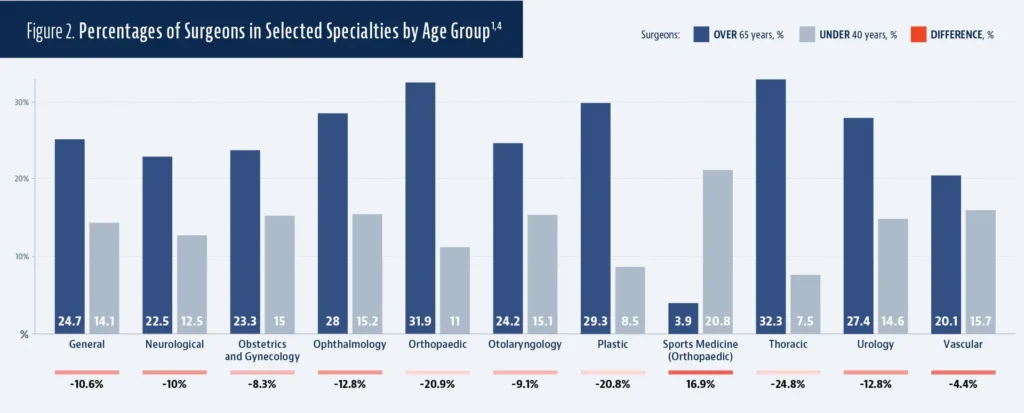
          At the end of 2022, 25.6% of surgeons were older than 65 years. That percentage was even higher for the subspecialties of ophthalmology, orthopedics, plastic surgery, thoracic surgery, and urology.As more Baby Boomer surgeons reach retirement age, the Association of American Medical Colleges (AAMC) projects that the U.S. will face a physician shortage of up to 86,000 providers by 2036.This impending gap signifies ample growth opportunities for new surgeons entering the field and a potential avenue for experienced surgeons to advance into leadership roles.

Surgeons aged 65+ outnumber their younger counterparts in every surgical specialty except Sports Medicine.
        • Expanded Patient Access

          As telemedicine becomes more widely available and accepted, surgeons can offer remote patient consultations to a broader population, and multidisciplinary specialist teams can collaborate virtually to help patients anywhere in the country.

          To further improve healthcare accessibility, some local governments and healthcare organizations offer incentives – such as scholarships, loan forgiveness, and stipend programs – to attract and retain surgeons in underserved regions.

      1. Groundbreaking Innovations
As medical technology rapidly advances, surgeons will have exciting new methods and protocols to explore in 2026. The use of AI in healthcare almost doubled in 2024 alone. New innovations offer streamlined decision-making, improved outcomes and recovery times, and groundbreaking new surgical solutions.
Examples include:
      • Robotic Surgery

        Robotic systems, such as the widely popular da Vinci surgical system, enable smaller incisions, greater precision, and faster patient recovery times.

      • Artificial Intelligence

        AI can improve surgical efficiency and patient safety by assisting surgeons with preoperative planning, imaging, and real-time analytics, as well as navigation during an operation.

      • Virtual & Augmented Reality (VR & AR)

        VR simulators create a realistic training environment for surgeons that poses zero risk to human patients. Studies have shown that VR training can improve procedural accuracy compared to traditional methods, leading to better patient outcomes and reduced liability risk for the surgeon.

        In the operating room, AR overlays of patient data and 3D anatomical models can be projected directly onto the surgery site, helping surgeons make accurate, data-driven decisions in real time.

Make Sure Your Malpractice Policy Keeps Pace with Changing Technologies

AI- and robotic-assisted procedures can improve efficiency and outcomes, but new technology also comes with risks. Safeguard your practice with strong coverage.

    1. High Earning Potential

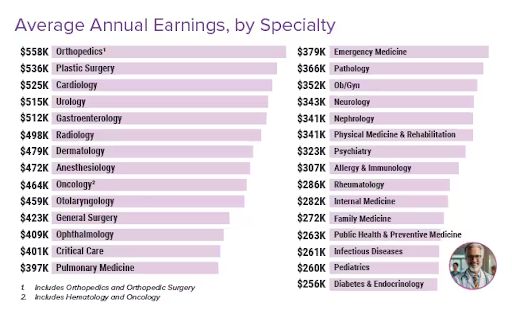
According to the Medscape Physician Compensation Report 2024, surgeons remain among the highest-paid healthcare providers due to their specialized skills and high level of responsibility.

Average Annual Earnings for U.S. Physicians & Surgeons

Average Annual Earnings By Speciality

Surgical specialties rank among the top-paid specialists in average annual earnings.
Source: 2024 Medscape Physician Compensation Report

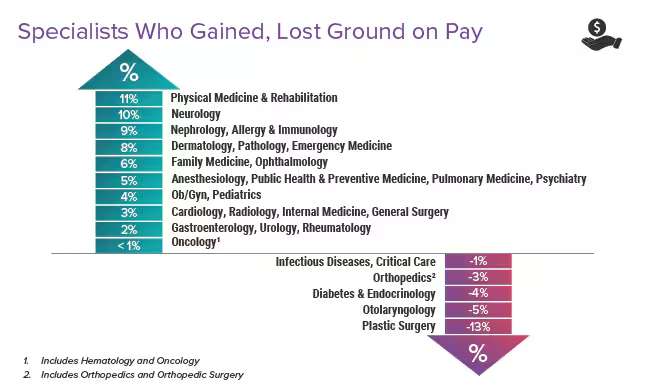
Change in Physician & Surgeon Pay by Specialty

Specialist compensation changes ranged from +11% to -13%, with some surgical specialities experiencing salary growth and others declining.
Source: 2024 Medscape Physician Compensation Report

Highlights from the 2024 Physician Compensation report include: 

  • Surgical salary growth outpaces nonsurgical salaries
    Between 2022 and 2023, total compensation for surgical specialists increased by 4.4%, while nonsurgical specialist compensation rose by less than 2%.

  • Orthopedic surgeons are the highest-paid subspecialists
    Subspecialties like orthopedic surgery and plastic surgery command the highest salaries, followed closely by general surgeons, OB/GYNs, and neurosurgeons.

  • Salary trends differ based on specialty
    Though plastic surgeons earn the second-highest average salary, the specialty experienced the largest downward trend (13%). 

  • Local demand and competition levels impact earning potential
    Surgeons are well-compensated in underserved regions with high demand and low competition, though urban hubs also offer high salaries due to the cost of living.

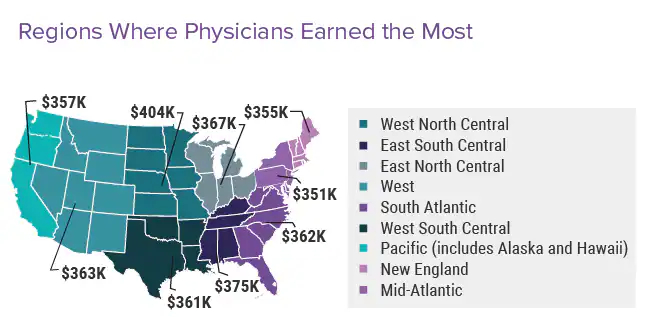
U.S. Physician Compensation by Region

The West North Central and East South Central regions largely consist of rural communities where physician competition is low, driving up salaries to attract and retain talent.
Source: 2024 Medscape Physician Compensation Report

Surgery Is a Rewarding Career That Requires Strong Risk Management

SURGPLI helps surgeons at every career stage secure strong coverage—without overpaying.

Professional Challenges for Surgeons in 2026

In 2026, surgeons will likely face obstacles related to industry trends, regulatory changes, and malpractice litigation precedents.

  1. Rigorous Commitment
    Obtaining the necessary education, training, and credentials to become a surgeon requires significant time commitments and substantial financial investment.

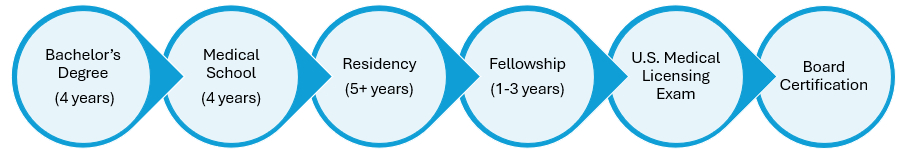
Education & Training Requirements to Practice Surgery Independently

Board-certified surgeons dedicate 14+ years to their training and education.

A commitment of this length and vigor requires personal sacrifice, often at the cost of work-life balance during the most intense phases. However, emerging trends such as mentorship programs, loan forgiveness policies, and VR-assisted training programs show promise for revolutionizing the process.

  1. Disruptive Regulatory Changes
    State and federal regulatory policies focusing on patient safety, quality of care, and financial reimbursement are influencing surgical practice in a variety of ways, such as:
    • Value-Based Care Payment Model
      As the fee-for-service model shifts to a value-based care model that links compensation to quality over quantity, surgeons are held more accountable for their care.January 1, 2026, TEAM (Transforming Episode Accountability Model), a new value-based model that impacts payments for Medicare patients undergoing certain surgeries, became mandatory in 188 geographic regions.
    • Reproductive Care
      For OB/GYN surgeons specifically, abortion legislation complicates patient care and liability exposure depending on their location. OB/GYNs must navigate a complex and evolving situation to minimize professional liability while delivering safe, compliant care to pregnant women.Abortion legislation also impacts provider shortages. According to a March of Dimes report, states where abortion is prohibited have fewer OB/GYNs per 10,000 births compared to states where abortion is less regulated. As of July 2025, 52% of U.S. counties lacked a single hospital with obstetric care.

      OB/GYNs in less-regulated states could see an increase in out-of-state and remote patients, which requires careful attention to state legal requirements and malpractice coverage parameters.
    • 2026 Medicare Reimbursement Adjustments
      After years of Medicare pay cuts, the 2026 Medicare Physician Fee Schedule includes a 2.5% increase effective January 1, 2026. However, that increase is largely offset by other cuts, including a 2.5% efficiency adjustment affecting nearly 91% of physician services. This cut will significantly reduce—or even eliminate—net gains for many practices.
  1. High-Risk, High-Liability Field
    The medical malpractice statistics of 2024 demonstrate the high liability landscape for surgeons:

Malpractice insurance premiums are expected to keep climbing in 2026.


Projected rate increases reflect the substantial risks of surgery and recent escalations in legal defense fees, social inflation, and nuclear payouts.

“Nuclear verdicts continue to increase at a drastic rate: The average of the top 50 medical malpractice verdicts was $32 million in 2022, $48 million in 2023, and an alarming $56 million in 2024.”
 -The Doctors Company

Safeguard Your Career with Premier Liability Coverage

SURGPLI brokers specialize in finding affordable, robust coverage for surgeons in high-risk specialties who are often targets for medical malpractice lawsuits. 

With strong malpractice insurance coverage, surgeons can focus on helping patients without worrying about professional liability exposure.

Surgery Career FAQs

It depends on a number of factors, including your location, subspecialty, experience, claims history, and risk tolerance.

SURGPLI brokers compare policies from A-rated carriers to find you the right solution. Request a free quote, email info@SURGPLI.com, or call 800-969-1339 to speak with someone in our Illinois office. 

Clear patient communication and meticulous records remain two of the most effective ways to reduce malpractice exposure across surgical specialties. Just as important is securing strong malpractice insurance—tailored to your location and specialty—as even the most skilled and experienced surgeons are not immune to malpractice claims.

While career paths are highly individualized, and a career as a surgeon comes with plenty of challenges, the surgical field offers a number of notable advantages for 2026, including high pay, career stability associated with increased demand, access to exciting new technologies, and the ability to impact patients’ lives. 

All surgeries carry some risk for the patient, so surgery is inherently a high-risk field, but some specialities are particularly vulnerable, including OB/GYN, general surgery, neurosurgery, orthopedic surgery, plastic surgery, bariatric surgery, ophthalmology, otolaryngology, and urology.

Contact us for a free evaluation or TAIL INSURANCE quote

Read the latest From SURGPLI

Surgery as a Career in 2026: Salary, Demand & Risk Outlook2026-06-11T05:48:40+00:00

Texas OB/GYN Surgeons Guide to Medical Malpractice Insurance

2025-07-23T17:55:50+00:00

Jump to a Section

GET A QUOTE

Medical Malpractice Insurance

This medical malpractice insurance guide outlines what Texas OB/GYN surgeons need to know, including key state laws, average premium costs, and specialty-specific liability risks. SURPLI brokers help Texas OB/GYNs secure the right coverage at the most competitive rates. Connect with a SURGPLI broker to review your options and get a quote.

You Focus on Patient Care. We’ll Handle Your Coverage.

Why Is Malpractice Insurance So Critical for Texas OB/GYNs?

OB/GYN is one of the highest-risk specialties. Nearly 80% experience at least one lawsuit during their careers.

Top 3 Most Common Causes of Lawsuits Include:

  1. Birth and delivery complications
  2. Gynecological surgery complications
  3. Missed diagnoses or delayed treatment

Over 40% of OB/GYNs reported at least one claim during training.
– National Library of Medicine

Because of increased exposure to lawsuits, Texas OB/GYN surgeons pay higher malpractice premiums than most other specialists.

A strong risk management strategy is essential. SURGPLI brokers provide the most critical pieces: comprehensive medical malpractice coverage tailored to your specialty.

Do Texas OB/GYNs Need Medical Malpractice Insurance?

While Texas law doesn’t require malpractice insurance, most healthcare facilities and surgical centers do, typically with standard limits of $1,000,000 per claim and $3,000,000 aggregate per year.

The Risk of Going Uninsured

Without comprehensive coverage, you’re exposed to devastating financial loss if sued.

SURGPLI recommends choosing an A-rated carrier to avoid:

  • Unexpected policy cancellation
  • Gaps in protection
  • Financial instability

What Does A-Rated Mean?

  • Strong financial backing
  • Long-term solvency
  • Proven history of protecting Texas OB/GYN surgeons

How SURGPLI Helps

  • Compares A-rated carriers
  • Finds coverage that fits your budget
  • Protects against specialty-specific liability risks

How Much is Medical Malpractice Insurance Cost for Texas OB/GYN Surgeons?

Premiums for Texas OB/GYN surgeons are among the highest in the state, varying based on location, surgical specialty, and claims history.

Specialty Approximate Annual Premium Approximate Tail Rate
OB/GYN $55,000 $110,000

*Using the TX standard limits of $1,000,000 Each Claim / $3,000,000 Aggregate per year in coverage. These rates are estimates only and can vary widely depending on the location and the claims history of each physician.  Quotes require a completed application and underwriter approval.

What Types of Malpractice Insurance Policies are Available for Texas OB/GYNs?

OB/GYNs in Texas can choose from these two primary types of medical malpractice coverage:

1. Claims-Made Insurance

Claims-made malpractice insurance provides coverage if the policy is in effect when the incident occurs and when the claim is filed. If a claim is filed after the policy date has ended, the claim is not covered.

  • If a claims-made policy ends – due to retirement, job change, or otherwise – you must purchase tail insurance to stay protected against future claims for past incidents. Tail coverage is purchased separately and typically requires a one-time cash payment of about 200% of the claims-made policy’s yearly premium.
  • Instead of tail coverage, you can opt to purchase nose coverage, or prior acts coverage, through your new carrier. This protects claims for incidents that occurred before the new coverage date, dating back to a specified date.
  • Claims-made policies are typically more affordable upfront, but rates increase annually.

2. Occurrence Insurance

Occurrence malpractice insurance provides coverage for incidents that occurred during the policy, regardless of when a claim is reported to the carrier.

  • Occurrence policies are more costly at the start of the policy, but the rate remains the same for the policy’s duration, and there is no need for tail coverage when the policy ends.

Don’t Let Insufficient Coverage Leave You Exposed

Every OB/GYN’s risk profile is different. SURGPLI helps Texas physicians secure the right coverage at the most competitive rate, without the guesswork.

Texas OB/GYNs: Top 5 A-rated Malpractice Insurance Carriers

SURGPLI brokers recommend carriers rated “A” or higher by A.M. Best. We recommend:

  • The Doctors Company 
  • Medical Protective (MedPro)
  • MagMutual
  • TMLT
  • ProAssurance Insurance Group

Texas Malpractice Damage Caps for OB/GYNs

  • Economic damages (like lost wages or medical bills) have no cap.

What Is the Statute of Limitations for Medical Malpractice Claims for Texas OB/GYN Surgeons?

Texas Code Title 4, Chapter 74 states that claimants must file a medical malpractice lawsuit:


  • Within 2 years from the date the malpractice occurred.
  • For ongoing treatment, within 2 years from the date the treatment concluded.
  • Minors under age 12 have until their 14th birthday to file a claim.
  • However, no claim may be filed more than 10 years after the date of the alleged act or omission, even for minors or those under a legal disability.

The Impact of Abortion Laws on Medical Malpractice Insurance for Texas OB/GYN Surgeons

Strict abortion laws in Texas increase liability risks for OB/GYNs, potentially causing higher premiums or limited coverage. Providers may need to consider higher policy limits or policy add-ons to ensure adequate coverage.


Liability Considerations for Texas OB/GYNs

Abortion Law Ambiguity

Vague terms like “medically necessary” make abortion difficult to interpret, leaving OB/GYNs exposed to legal risks.

What You Can Do

Consult your broker to ensure your policy limits reflect today’s heightened legal risks.

Telemedicine Liability  

Treating patients out of state via telemedicine could expose you to additional liability.

What You Can Do

Confirm your policy covers interstate telemedicine consultations and prescriptions. If not, ask about adding a rider or endorsement.

Lack of Criminal Coverage

Texas OB/GYNs can face criminal charges for abortion-related care, and standard malpractice insurance typically doesn’t cover criminal defense.
What You Can Do

Ask if your insurance provider offers criminal defense coverage as an add-on.

SURGPLI defends surgeons in high-stakes situations by ensuring your policy provides the protection you need, when you need it most.

SURGPLI Helps Texas OB/GYN Surgeons Save Time and Money

SURGPLI brokers:

  • Compare coverage, rates, and A-rated carriers that understand the specific risks Texas OB/GYNs face.
  • Find applicable discounts, including those for new practices, medical association members, and surgeons with no previous claims. Some of our carrier partners also offer risk management incentives and CME credits.
  • Evaluate flexible payment plans to match your practice’s cash flow and budget needs.

Consult with you on all quotes and options, so you can find the best coverage and rate for your needs.

Protect your practice and your livelihood with comprehensive coverage.

From quote to coverage, we’ll ensure you get the best coverage at a competitive rate.

Read the latest From SURGPLI

Contact us for a CA MEDICAL MALPRACTICE INSURANCE quote

Texas OB/GYN Surgeons Guide to Medical Malpractice Insurance2025-07-23T17:55:50+00:00

Arizona Surgeons Medical Malpractice Insurance Buying Guide 2024

2024-12-23T19:06:05+00:00

Jump to a Section

Choose SURGPLI as Your Medical Malpractice Insurance Broker

If you are a physician needing medical malpractice coverage in Arizona, MEDPLI will work for you as your only trusted broker. Use the information in this 2024 Buying Guide to get ready to discuss your medical malpractice insurance needs with a MEDPLI broker. Get a quote.

GET A QUOTE

Medical Malpractice Insurance

Arizona Medical Professional Liability Insurance Market Summary

The Arizona medical malpractice insurance market is dominated by one carrier, MICA (Mutual Insurance Company of Arizona), but there are other great options for physicians which offer excellent coverage, greater portability (if you move states, for example), and pricing. We recommend carriers rated “A” by A.M. Best because of their long-term financial solvency and a history of providing robust financial and legal support for Arizona physicians.

Some of the top-rated medical malpractice insurance companies serving Arizona physicians include:

  • Norcal Group (A Part of ProAssurance)
  • AMS RRG
  • Coverys Group
  • MedPro Group
  • The Doctors Company
  • Admiral Insurance Co
  • ProAssurance

Save time and effort by getting a wide range carrier quotes through MEDPLI as your single point of contact. You can get a quote through us today.

Malpractice Insurance Rates for Arizona Doctors

This information includes general estimated premiums which can vary greatly based on many factors, such as practice location, medical/surgical specialty, and past claims history. Talk to a MEDPLI broker to get quotes tailored to your unique coverage needs.

Specialty Approximate Rate
Anesthesiology $28,000
Cardiovascular Disease Minor Surgery $31,000
Emergency Medicine $38,000
Family Practice No Surgery $18,000
Gastroenterology $26,000
General Surgery $51,000
Internal Medicine No Surgery $18,000
Neurology No Surgery $18,000
Obstetrics and Gynecology Major Surgery $69,000
Occupational Medicine $12,000
Ophthalmology No Surgery $12,000
Orthopedic Surgery No Spine $48,000
Pediatrics No Surgery $18,000
Psychiatry $15,000
Radiology – Diagnostic $29,000
Plastic Surgery $45,000

*Using the AZ standard limits of $1,000,000 Each Claim / $3,000,000 Aggregate per year in coverage.

Each practice risk profile is different, and your rates could vary significantly. MEDPLI specializes in medical malpractice insurance and tail insurance coverage for Arizona physicians and surgeons. To get estimates based on your specific scenario, reach out for a personalized quote. Get a quote.

GET A QUICK QUOTE

Arizona Medical Malpractice Insurance

Types of Professional Liability Insurance for Arizona Physicians

Here is a brief overview of the most common types of medical malpractice insurance for physicians in Arizona:

Claims-Made Insurance
Claims-made malpractice insurance provides coverage if the policy is in effect when the incident took place AND when the claim is filed. If a claim is filed after the end of the policy date, the claim is NOT covered. With a claims-made policy you need tail malpractice insurance, which is a separately purchased insurance policy or endorsement, to make sure you have full protection. Learn more about claims-made insurance here.

Occurrence Insurance
Occurrence malpractice insurance provides coverage for incidents that occurred during the policy year, regardless of when a claim is reported to the carrier. Occurrence policies are more costly at the start of the policy, but the rate stays the same for the length of the policy, and there is no need for tail coverage when the policy ends. Read more about occurrence insurance.

Tail Insurance

Since most malpractice insurance policies are underwritten on a claims-made basis, you will be exposed to a lawsuit if a former patient files a claim against you and you do not secure tail coverage. When you are preparing to leave your employer, you should seek tail coverage options with an independent broker like MEDPLI. Tail insurance covers you for a specific time period. The new employer’s policy is not going to cover you for prior acts of a former practice, hence tail coverage is needed. Read more about tail malpractice insurance for physicians.

Reach out to an experienced MEDPLI broker who will work for you to find a tail policy at a great price.

Telehealth Laws in Arizona

The state created the Arizona Telemedicine Program (ATP) at the University of Arizona in 1996. Since then, because of the robust support that ATP has been able to provide, multiple medical specialty services are offered via telemedicine to Arizona’s rural areas. Healthcare systems across Arizona have been able to benefit from the state’s early focus on telehealth as an emerging technology.

In May 2021, Arizona Governor Doug Ducey signed A.R.S. 36-3606 into law, allowing physicians licensed in other states to obtain a temporary license to provide telehealth services in Arizona if they comply with certain conditions. Out-of-state physicians practicing telemedicine in Arizona must provide proof of licensing in their home state, as well as proof of liability coverage, among other requirements.

Currently, Arizona’s telehealth laws mandate that Arizona physicians must:

  • Be licensed to practice medicine in the State of Arizona.
  • Be in compliance with the Arizona’s requirements regarding the maintenance of liability insurance.
  • Obtain verbal or written informed patient consent prior to the telehealth virtual visit.
  • Ensure that the patient’s verbal or written consent, plus notes on the telehealth services provided, are entered in the patient’s medical record.

Doctors that take care of patients via telehealth are subject to the same liabilities as with in-person treatment. Reach out to a MEDPLI insurance broker to make sure your existing medical malpractice policy extends coverage to perform telehealth services in Arizona.

Arizona’s Statute of Limitations for Medical Malpractice Claims

The statute of limitations for medical malpractice in Arizona can be complex and can vary from case to case. Consulting with MEDPLI insurance brokers who understand the ins and outs of this system is an important part of protecting your medical practice with strong medical malpractice insurance coverage.

Medical Malpractice Insurance Outcomes

The total malpractice payout in Arizona was $43,610,000 as of 9/30/2023 (Source: National Practitioner Data Bank).

Need Medical Malpractice Insurance in Arizona? Request a Quote Today

Keep in mind, however, that Arizona does not have damage caps in medical malpractice lawsuits. That’s why Arizona physicians and surgeons – especially those who practice in higher-risk specialties – need strong medical malpractice insurance. Talk to a SURGPLI insurance broker who will help you shop for competitive quotes on robust coverage aligned with your specialty.

Get a fast quote for medical malpractice insurance or call 1-800-969-1339.

SURGPLI is a division of MEDPLI, an independent insurance brokerage that specializes in making medical malpractice insurance simple for doctors.

Max Schloemann

About the Author

Max Schloemann is a medical malpractice insurance broker, focused on helping physicians secure Medical Professional Liability coverage. He helps Doctors and Surgeons, as well as Physician Assistants, Nurse Practitioners, and healthcare entrepreneurs launch new medical practices across the country. Max graduated Magna cum Laude from Southern Illinois University College of Business and was named the Outstanding Management Senior. Max’s career in medical malpractice insurance began in 2008 with an industry-leading firm. Max founded SURGPLI in 2023 to help surgeons navigate the complexities of medical malpractice insurance in the new era of healthcare. Max’s wife, Kristen, a Physician Assistant, and their 4 kids (plus 1 dog) enjoy hiking, golf, and cooking.

Read the latest From SURGPLI

Contact us for a CA MEDICAL MALPRACTICE INSURANCE quote

Arizona Surgeons Medical Malpractice Insurance Buying Guide 20242024-12-23T19:06:05+00:00
Go to Top